How to Write a Business Plan That Impresses Investors

In short: A business plan for investors should explain how a company will actually make its goals happen, not just what it wants to achieve. Most business plans stop at the goals. However, the stronger ones connect the customer problem, product, market, business model, operating assumptions and financial projections into one coherent system. Therefore, this guide explains how to write a business plan for investors by moving beyond optimistic targets and corporate storytelling. In addition, it covers what investors look for in a business plan, the essential components of a business plan, financial projections, fundraising requirements, common mistakes, and how Venture Care approaches business plan review.
Most business plans do not fail because founders lack ambition. Instead, they fail because ambition gets mistaken for a plan. Consider statements like these:
- “We will scale rapidly.”
- “We will also hire top talent.”
- “We will capture a significant share of the market.”
- “We will reach ₹100 crore in revenue.”
- “Finally, we will achieve healthy margins.”
Admittedly, these statements may all be reasonable goals. However, they do not explain what has to happen for those goals to become real.
That distinction is easy to miss when writing a business plan for investors. It is also one of the reasons so many plans sound convincing on paper but become difficult to defend when an investor starts asking questions.
The Problem With Frictionless Optimism
This problem is what we might call frictionless optimism. The business plan assumes that customers arrive when expected, employees perform at full capacity, sales cycles remain predictable, competitors do not react, costs remain under control and cash arrives before the business needs it. As a result, the plan tells a smooth story. Real businesses, on the other hand, are rarely smooth.
If you are trying to understand how to write a business plan for investors, the objective should therefore not be to make the company sound bigger, faster or more certain than it is. Instead, the objective is to make the business understandable.
Above all, an investor should be able to see how the business creates value, how that value becomes revenue, what resources are required to deliver it, what could slow the system down, how much capital is needed and what that capital is expected to change. In other words, a business plan should not just describe the destination. Rather, it should explain the machinery that gets you there.
What Investors Are Really Testing in a Business Plan
To begin with, there is no universal investor formula. For example, a pre-revenue startup will naturally have different evidence from a company with several years of operating history. Likewise, a SaaS business will have different economics from a manufacturing company.
Still, the underlying questions are remarkably consistent. Who is building this business? What problem are they solving? Who has that problem? Why will customers pay to solve it? How large is the opportunity? How will customers be acquired? What has already been demonstrated? What makes the business defensible? How does the company make money? And what happens when it receives additional capital?
Moreover, these questions are connected. First, the problem creates the need for the product, and the product creates customer value. In turn, that customer sits inside a market, which creates the opportunity. Next, the business model turns customer value into revenue, while the go-to-market strategy explains how those customers are acquired. The financial model then translates those assumptions into numbers. Finally, the fundraising requirement explains what additional capital allows the company to do.

Ultimately, that connection is what makes a business plan for investors useful.
Ask What Has to Be True
For instance, consider a company projecting ₹100 crore in revenue three years from now. The interesting question is not whether ₹100 crore sounds ambitious or achievable. Instead, the interesting question is: what has to be true for ₹100 crore to exist?
- How many customers are required, and what will they pay?
- How long does it take to acquire them?
- How many salespeople are needed, and when?
- What will retention look like after the first year?
- How much working capital will the business require?
- What happens if the sales cycle is longer than expected?
Once you start asking those questions, the business plan for investors changes. Consequently, it stops being a document that describes an outcome and becomes a model that explains how the outcome is produced.
That is also why traction matters. Revenue, customer growth, retention, signed contracts, pilots, product usage and repeat purchases are useful because they provide evidence about how the system is actually behaving. In short, a good plan keeps a clear line between what the business has already demonstrated and what it expects to happen next.
Start Your Business Plan for Investors With the “Done” State
One of the most common mistakes in planning is treating growth as the destination: more customers, more employees, more revenue, more locations, more funding. All of these measure movement. However, none of them necessarily defines success.
Before building the financial model, ask a more fundamental question: what does a sustainable version of this business look like?
Imagine a company reaches ₹100 crore in revenue but requires another fundraising round every year simply to stay alive. Alternatively, it has 500 employees but the founder still has to approve every important decision. Or it acquires thousands of customers but loses them almost as quickly as it acquires them. In each case, the company has grown. But has the system actually worked?
Therefore, a useful business plan for investors should define the end state across several dimensions. What does the steady-state business look like? How does it create and retain value? Why do customers stay? How can employees perform without constant founder intervention? What allows the company to generate enough cash or capital to keep operating? And what ultimately makes the business valuable to its capital providers?
A Sustainable Business Is an Economic System
This matters because a sustainable business is an economic system, not simply a revenue number. Each participant needs a reason to stay in it:
- Customers need a reason to pay, and to keep paying.
- Employees need a reason to stay and perform well over time.
- Suppliers and partners need commercially viable relationships.
- The company needs sufficient margin and cash generation to operate and reinvest.
- Capital providers, finally, need a credible path to value creation.
The exact balance differs from business to business, but the principle remains the same. In other words, the system should not require permanent external life support. Paul Graham’s essay Default Alive or Default Dead? makes a similar point: founders should know whether their current growth and spending can reach profitability on the money they already have.
Funding Should Help the Company Cross a Threshold
This becomes particularly important when writing a business plan for raising capital. The purpose of funding should not simply be “to grow.” Instead, capital should help the company cross specific operating thresholds.
For example, it might fund a product that unlocks a new customer segment. Alternatively, it might allow a proven sales process to become repeatable by building a sales team. Or it might provide working capital when a business has to pay suppliers or purchase inventory well before customers pay.
The capital should have a job. And that job should be visible in the plan.
Build Your Business Plan for Investors Around Friction
Once the destination is clear, the next question is whether the route to it survives contact with reality. This is also where many founders write a business plan for investors that is too optimistic.
After all, people have limits. Customers delay decisions, and employees leave. Sales cycles stretch, suppliers increase prices and product launches slip. Meanwhile, competitors respond and customers pay late. However, these are not extraordinary events. Instead, they are normal operating conditions. As a result, a plan that works only when everything happens on schedule is not necessarily a strong plan.
Human Friction
Take hiring, for example. A founder might write that the company will hire 20 salespeople and double revenue. But hiring a salesperson does not create revenue on the day the person joins.
First, the employee needs to understand the product, learn the sales process, build a pipeline, meet prospects and close deals. Some people will perform better than others, and some will leave. A realistic plan therefore needs to account for the time between hiring and productivity. That gap is what we call human friction.
Economic Friction
There is also economic friction. Revenue can be recognised before cash is collected. A manufacturer may have to purchase inventory before receiving payment. Similarly, an enterprise customer may negotiate 60- or 90-day payment terms, and a company may need to hire ahead of revenue. The business can therefore look healthy on paper while its bank balance is moving in the opposite direction.
Market Friction
Then there is market friction. Customers already have alternatives: existing suppliers, internal processes, contracts, habits and switching costs. For example, a competitor may cut prices after your launch. A customer may even agree that your product is better and still decide that changing systems is not worth the effort this quarter. Therefore, any business plan has to account for these forces.
Design the system to function in spite of friction, not in the absence of it.
That does not mean writing a pessimistic business plan. Instead, it means writing one that can survive reasonable scrutiny.
How to Write a Business Plan for Investors: From Aspiration to Mechanism
Above all, this is the central shift in learning how to write a business plan for investors. Instead of asking only what the company wants to achieve, ask what mechanism produces the outcome. For this, a useful mental model is:
Event A → Mechanism B → Friction C → Outcome D
Consider this statement: “We will grow revenue by expanding our sales team.” It sounds reasonable. But it is still only a description. Now, by contrast, consider a more engineered version:
“We plan to add 10 enterprise sales representatives over the next 12 months. New representatives are expected to take approximately four months to reach productivity. Each productive representative is expected to generate ₹50 lakh in annual contract value. Because our current enterprise sales cycle averages six months, the financial model delays the majority of incremental revenue until after the expected ramp period.”

As a result, an investor can now interrogate the assumptions:
- Can the company hire ten people?
- Is four months a realistic ramp period?
- Why should each salesperson generate ₹50 lakh?
- Does the existing sales process also support that volume?
- And what happens if only seven people reach target, rather than ten?
Notably, the second statement is not necessarily more optimistic. It is simply more useful because the mechanism is visible. That is exactly what a business plan for investors should do. In other words, it should make the assumptions inspectable.
What Should a Business Plan for Investors Include?
The exact components of a business plan for investors depend on the company’s stage, industry and business model. Even the U.S. Small Business Administration’s business plan guide notes that there is no single right format. Still, a startup preparing an investor-ready business plan will generally need to cover the executive summary, company overview, problem, solution, market opportunity, customer segments, business model, go-to-market strategy, competition, traction, team, financial projections, funding requirement, use of funds, risks and milestones.
However, these should not be treated as isolated boxes. First, the company overview establishes where the business stands today. Next, the problem section should explain a specific customer pain rather than simply saying that a market is inefficient. The solution then needs to show how the product addresses that problem and what measurable outcome it creates.
Make the Problem Specific
For example, saying that “small businesses struggle with financial management” is broad. By contrast, a stronger explanation might describe small retailers relying on spreadsheets and manual reconciliation to track inventory, supplier payments and cash flow. As a result, the problem becomes specific. It now has a customer, a process and a consequence.
The product can then be explained against that problem:
Customer problem → Product intervention → Measurable outcome
If the product reduces invoice processing from three days to four hours, say so.
Sounds polished
“Optimises workflows.”
Gives an investor something to evaluate
“Reduces invoice processing time from three days to four hours.”
Size the Market Honestly
The same principle applies to market analysis. After all, a large TAM is not evidence that a company can capture a large market. Instead, the plan should distinguish between the total addressable market, the portion the company’s product can actually serve and the portion it could realistically capture. Stripe’s guide to TAM, SAM and SOM lists confusing TAM with SAM among the most common market sizing mistakes.

The initial customer should also be specific. For B2B companies, that might mean industry, company size, geography, revenue, technology environment and decision-maker. For B2C businesses, by contrast, demographics, location, income, behaviour and purchase frequency may matter more.
Similarly, a credible business plan for investors does not need to claim that everyone is a potential customer. Rather, it needs to explain who is most likely to buy first.
The Business Model Has to Survive Contact With Reality
A business model should answer a basic question: how does the company make money? In practice, that means explaining revenue streams, pricing, average order or contract value, subscription structure where applicable, gross margins, recurring versus one-time revenue and payment terms.
If there are several potential revenue streams, explain which one is expected to become the primary economic engine. Simply listing “multiple monetisation opportunities” is not enough.
Go-to-Market Needs a Mechanism Too
Then comes go-to-market. Likewise, “we will use digital marketing” is not a complete strategy. Instead, the plan should connect the customer to the acquisition channel, conversion process, revenue and retention.
For a B2B company, for instance, this might involve enterprise sales, demonstrations, pilots, partnerships and referrals. If the average enterprise sales cycle is six months, that delay should appear in the financial model.
Suppose 40 companies enter a pilot and eight become paying customers. That 20% conversion rate then provides a starting point for future assumptions. In fact, it is evidence. The plan can then distinguish between what is already working and what remains a hypothesis.
Moreover, that distinction becomes increasingly important as the company raises more capital. A founder can reasonably make assumptions about an untested market at an early stage. However, those assumptions should not be presented as established facts.
Financial Projections in a Business Plan for Investors Should Explain the Business
However, financial projections are often where a business plan for investors becomes disconnected from reality. For example, a founder writes:
- Year 1: ₹5 crore
- Year 2: ₹15 crore
- Year 3: ₹40 crore
The numbers may look impressive, but they do not explain what produces them. By contrast, a stronger model begins with operating assumptions:
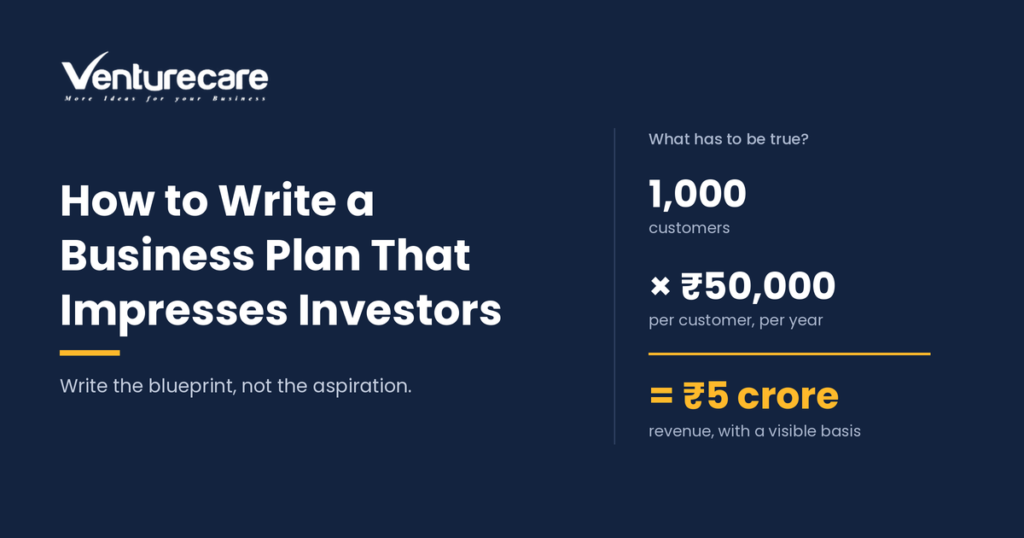
Customers × Average Annual Revenue Per Customer = Revenue
If the company expects 1,000 customers paying ₹50,000 annually, the ₹5 crore forecast has a visible basis. As a result, the investor can now challenge the assumptions. Can the company acquire 1,000 customers, and at what cost? How many salespeople are required? What is the conversion rate? How long does acquisition take? And how many customers remain after one year?
That is why financial projections should be the numerical version of the business strategy. Consequently, a business plan for investors may need to cover revenue, cost of goods sold, gross profit, gross margin, operating expenses, operating profit, cash flow, burn rate, cash balance, runway, CAC, LTV, CAC payback period, break-even point and capital requirements.
Unit Economics Connect Growth to Economics
Unit economics are particularly useful because they connect growth to economics. David Skok’s SaaS Metrics 2.0 is a widely used reference on how these metrics relate to each other.
| Metric | What it tells an investor | How it is calculated |
|---|---|---|
| Customer Acquisition Cost (CAC) | What it costs to win one new customer | Total sales and marketing expenditure ÷ new customers acquired |
| Lifetime Value (LTV) | The economic value a customer generates over the relationship | Varies by model; recurring businesses may use revenue, gross margin, retention and customer lifespan |
| CAC payback period | How long it takes to recover the acquisition cost | Time for gross profit from a customer to cover its CAC |
| Cash runway | How long the company can operate on current cash | Available cash ÷ monthly net burn |
Profit Is Not the Same as Cash
Then there is cash. However, profit is not the same as cash. A company can have strong revenue growth and still run out of money because customers pay slowly, inventory requirements rise or hiring happens before revenue arrives.
For example, a simplified runway calculation is:
Cash Runway = Available Cash ÷ Monthly Net Burn
If a company has ₹6 crore available and burns ₹50 lakh a month, its simple runway is approximately 12 months.

Plan for Base, Upside and Downside Cases
Even so, a good model should also ask what happens when assumptions change:
- What if revenue is lower?
- What if the sales cycle extends?
- What if hiring takes longer?
- What if payment terms become less favourable?
That is why base, upside and downside cases are useful. Still, they are not attempts to predict the future with precision. Rather, they show how the system behaves when reality differs from the plan.
Capital Should Have a Job
A business plan for raising capital should answer four straightforward questions. How much are you raising? Why now? Where will the money go? And what should it help you achieve?
Of these, the fourth question is often the most important. If ₹2 crore goes into product development, what product milestone does that capital fund? If ₹2 crore goes into sales, how many people will be hired, how long will they take to become productive, what customers will they target and what commercial result is expected?
An aspiration
“We need ₹10 crore to scale.”
A mechanism
“We are raising ₹10 crore to fund 18 months of product development, sales hiring and working capital, with the base case taking the company from X customers to Y customers and from ₹A revenue to ₹B revenue.”
Clearly, the second version gives investors something to evaluate. It also forces the founder to think more clearly about the amount being raised. That is why use of funds should connect directly to milestones.
Capital is not the outcome. Instead, it is an input into the operating system.
Risks Belong Inside a Business Plan for Investors
A serious business plan for investors does not pretend risk does not exist. Instead, it identifies the risks that could materially affect the business and explains how management intends to respond.
For example, these could include rising acquisition costs, customer concentration, regulation, supplier dependence, technology challenges, hiring constraints, long sales cycles, competitive responses or working-capital requirements.
However, the important part is what happens next. If enterprise sales cycles extend beyond six months, perhaps the company maintains a larger pipeline and develops a smaller product package that can be sold through a shorter process. If customer concentration is high, the company might set a target for reducing the percentage of revenue coming from its largest accounts. Risk becomes useful when it changes the operating plan.
Set Milestones You Can Measure
Similarly, the same principle applies to milestones. “Expand the business” is vague. By contrast, “Reach ₹10 crore ARR by the end of FY2028” is measurable. A good milestone tells the reader what changes, by when, and why that change matters.
Common Mistakes in a Business Plan for Investors
However, the most common mistakes in a business plan for investors are usually not formatting mistakes. Instead, they are thinking mistakes.
- Unrealistic projections. Aggressive growth is not a problem by itself. However, aggressive growth without a mechanism is.
- Treating TAM as revenue. After all, a large industry does not mean the company will capture a large share of it.
- Ignoring competition. Customers always have alternatives, including continuing to use their existing process or doing nothing.
- Hiding weak metrics. A weak number can become useful information when the company can explain why it happened, what was learned and what changed.
- Excessive jargon. Indeed, a sophisticated business does not need complicated language to explain itself.
- Strategy and financials telling different stories. If the plan describes a six-month enterprise sales cycle but the financial model assumes immediate revenue from thousands of customers, the disconnect is obvious.
In the end, a strong business plan for investors is not one where every number looks perfect. Instead, it is one where the assumptions, strategy, financials and risks make sense together.
Venture Care’s Business Plan Review Process
At Venture Care, business plan review should go beyond polishing a document before it reaches investors. Instead, the more important question is whether the underlying business story holds together.
A review can examine the business model, market opportunity, product positioning, customer segments, competitive landscape, go-to-market strategy, traction, financial projections, fundraising strategy and overall investor readiness. But the purpose is not simply to check whether these sections exist. Rather, it is to pressure-test the logic connecting them:
- Does the product actually address the stated customer problem?
- Are the market assumptions reasonable?
- Is there a practical route to acquiring customers?
- Are the right metrics being used for the company’s stage?
- Do revenue, costs, margins, burn and runway connect?
- Is the capital requirement tied to specific milestones?
That is also where a business plan review becomes valuable. For founders preparing a business plan for raising capital, investor questions often expose gaps that were already present in the underlying business model. The objective is not to make the business sound better than it is. Instead, it is to make the business easier to understand and easier to evaluate.
A Practical Business Plan Template for Startups
If you are building a business plan template for startups, a useful structure is:
- Start with the executive summary and company overview.
- Next, set out the problem and customer need, followed by the solution and product.
- Then size the market opportunity and define your customer segments.
- After that, explain the business model, go-to-market strategy and competitive landscape.
- Next, show your traction and introduce the team.
- Then add financial projections, unit economics, and cash flow and runway.
- Finally, state the funding requirement, use of funds, risks and mitigation, and milestones.
Do not treat the template as a formula, though. For example, a pre-revenue startup may need to spend more time proving the problem, customer and product. On the other hand, a company with meaningful revenue may need much deeper analysis of retention, margins, CAC, LTV, working capital and cash flow. In other words, the structure should follow the business. After all, the template is only there to make sure important questions are not missed.
Three Questions to Pressure-Test Your Business Plan for Investors
Finally, before sending the document to an investor, ask three questions.
1. What has to be true for our main outcome to happen?
If the answer is simply “we will grow”, the mechanism is missing. Instead, break the outcome down into customers, people, capital, processes, timing and economics.
2. What happens when reality does not cooperate?
Consider what changes if hiring takes longer, customers delay payment, conversion falls, the sales cycle extends or competitors respond. If the plan only works under perfect conditions, then it is not finished.
3. Can someone challenge every major assumption?
Where did the revenue forecast come from? Why will customers buy? How will they be acquired? What supports the margin assumption? Why is the funding amount sufficient? What happens if the base case is wrong? However, if the answer is evidence, logic and a clearly explained mechanism, then the plan is doing what it should.
Final Takeaway: A Business Plan for Investors Is a Blueprint, Not an Aspiration
In the end, learning how to write a business plan for investors is ultimately about learning how to explain how a business works.
- Do not write that you will become a market leader. Explain what has to happen for that position to become possible.
- Do not write that you will scale the sales team. Explain the hiring, ramp period, quota, sales cycle and economics behind the expansion.
- Do not write that you will reach ₹100 crore in revenue. Show the customers, pricing, acquisition, retention and timing that produce ₹100 crore.
Ultimately, the strongest business plan for investors does not eliminate uncertainty. Instead, it makes uncertainty visible. It also does not pretend friction will disappear; rather, it shows how the business is designed to operate despite it. Finally, it does not ask an investor to believe an aspiration simply because it sounds compelling. Instead, it shows the mechanism.
Do not write an aspiration. Write an engineering blueprint.
Above all, that is what turns a business plan from fundraising material into a useful explanation of the business itself.
Want investors to see the mechanism behind your plan?
Venture Care’s business plan team pressure-tests the logic connecting your market, model, financials and funding ask, so the plan holds up when investors start asking questions.
Related reading:
- The Art of Pitch Deck Storytelling: Winning Investor Hearts
- 8 Best Business Plan Services for Small Businesses and Startups
- Effective Investor Communication Strategies for Building Lasting Relationships
Frequently Asked Questions About a Business Plan for Investors
What is an investor-ready business plan?
An investor-ready business plan, or business plan for investors, explains how a company works, who it serves, how it makes money, what it has demonstrated, what risks it faces and how additional capital will be used. In addition, it connects the company’s strategy, operating assumptions and financial projections.
How do you write a business plan for investors?
To understand how to write a business plan for investors, start with the problem, customer, solution, market and business model. Then explain the go-to-market strategy, traction, team, financial projections, funding requirement, use of funds, risks and milestones. Above all, the key is to explain the mechanism behind the expected outcomes.
What should a business plan for investors include?
The main components of a business plan for investors generally include an executive summary, company overview, problem, solution, market opportunity, customer segments, business model, go-to-market strategy, competitive analysis, traction, team, financial projections, funding requirement, use of funds, risks and milestones.
What is a business plan for raising capital?
A business plan for raising capital explains how much funding a company needs, why it needs the capital, how the funds will be used and what milestones the funding should help achieve. In addition, the funding requirement should connect directly to the company’s operating and financial plan.
What makes a business plan impressive to investors?
An effective business plan for investors makes the business easy to understand and its assumptions easy to evaluate. In particular, investors need to see a logical connection between the customer problem, solution, market, business model, traction, financial projections and funding requirement.
What is a good business plan template for startups?
A practical business plan template for startups can include the executive summary, company overview, problem, solution, market opportunity, customer segments, business model, go-to-market strategy, competitive landscape, traction, team, financial projections, unit economics, cash runway, funding requirement, use of funds, risks and milestones.
What financial projections should a business plan for investors include?
Financial projections may include revenue, cost of goods sold, gross profit, gross margin, operating expenses, operating profit, cash flow, burn rate, cash runway, CAC, LTV, CAC payback period, break-even point and capital requirements. However, the numbers should always be connected to clear operating assumptions.
Why are cash flow and runway important in a business plan?
After all, revenue does not automatically create cash. Payment cycles, inventory, hiring and working capital can create cash requirements even when revenue is growing. Cash flow and runway show whether the company can continue operating while executing its plan.
What are common business plan mistakes?
Common mistakes include unrealistic projections, treating TAM as expected revenue, ignoring competition, hiding weak metrics, using excessive jargon, separating strategy from financial projections and ignoring cash flow. Another major mistake is describing an outcome without explaining the mechanism required to achieve it.
How should a startup explain its market opportunity?
A startup should distinguish between TAM, SAM and SOM and explain how each figure was calculated. Then, it should also identify the specific customer segment it intends to serve initially rather than relying only on a large industry-wide market figure.
Should risks be included in a business plan for investors?
Yes. A credible business plan for investors should identify material risks and explain how the company intends to manage them. For example, these may include customer concentration, competition, long sales cycles, hiring constraints, regulation, supplier dependence, technology challenges and working-capital requirements.
How can Venture Care help with business plan review?
Venture Care’s business plan review process can examine the business model, market opportunity, customer problem, product positioning, competition, go-to-market strategy, traction, financial projections, fundraising strategy and investor readiness. Above all, the objective is to identify gaps in the underlying business logic and make the plan easier for investors to understand and evaluate.